
নোড এর বিষয়বস্তু উন্নত করতে চান? একটি সম্পাদনা অনুরোধ করার চেষ্টা করুন.
A profound structural reorganization is redefining the global technology sector. Aggregate revenues for eighteen of the world's largest technology providers surged by an unprecedented 28.3 percent year-over-year, reaching 694 billion dollars in the single most recent quarter. This growth trajectory far outpaced high-end analyst projections of 21.8 percent, establishing the most rapid quarterly expansion the technology sector has recorded since 2010. Fifteen of the tracked enterprises surpassed their maximum financial guidance, with ten companies setting all-time revenue records. This financial surge signals a fundamental transition in artificial intelligence economics: the enterprise market has decisively migrated from speculative, experimental proofs-of-concept to scaled, live production environments. However, this massive influx of capital has exposed a stark corporate paradox. Rather than expanding payrolls to match record profits, technology conglomerates are simultaneously executing deep workforce reductions. During the same quarterly period, four major technology giants collectively eliminated 58,000 corporate roles. Enterprise software pioneer Oracle decoupled roughly 18 percent of its workforce to preserve operational margins while redirecting capital toward a projected 50 billion dollar data center infrastructure expansion. Microsoft similarly signaled impending headcount reductions even as its annualized artificial intelligence revenue run rate climbed by 123 percent to 37 billion dollars. This asymmetric reallocation of corporate resources proves that the tech economy has transitioned away from human-centric scaling models. Corporate capital is being systematically stripped from legacy personnel lines and funneled directly into massive infrastructural capital expenditures, specialized compute hardware, and high-performance networking fabrics necessary to host next-generation autonomous agentic architectures.
The Great Relayering of Enterprise IT Architecture
The record-breaking financial performance of global technology vendors marks the official end of the exploratory phase of enterprise artificial intelligence. For the past several years, corporate investments in machine learning were characterized by heavily subsidized pilot programs, internal research sandboxes, and highly localized experiments. The data compiled by Omdia confirms that this paradigm has collapsed in favor of industrialized deployment. The 28.3 percent year-over-year revenue leap to 694 billion dollars across 18 major tech titans demonstrates that artificial intelligence is no longer a speculative line item on balance sheets; it has become the core infrastructure driving enterprise IT spending.
This spending wave is expressing itself unevenly across different layers of the technology stack. At the foundation, demand for raw computational power has mutated from a competitive advantage into a baseline requirement for corporate survival. Nvidia recorded a staggering 75 percent year-over-year increase in data center revenue, reaching 62 billion dollars in a single quarter. This sustained hyper-growth demonstrates that the expected cooling of GPU demand has failed to materialize. Instead, enterprise buyers are accelerating their hardware acquisition cycles, driven by fear of systemic supply shortages and the technical requirements of training and running localized foundation models.
Crucially, the hardware purchasing mix is evolving. While Nvidia graphics processing units remain the primary currency of modern computing, enterprise buyers are rapidly diversifying into custom application-specific integrated circuits, high-performance networking architectures, and advanced memory systems. Dell Technologies saw its artificial intelligence-optimized server revenue skyrocket by 342 percent to reach 9 billion dollars during the quarter. This exponential spike indicates that corporate buyers are no longer merely purchasing individual chips; they are procuring fully integrated, industrial-scale computational clusters capable of handling sustained, high-throughput training and inference workloads.
This hardware foundation is directly feeding cloud infrastructure providers, who are reporting unprecedented acceleration in their core business units. Google Cloud revenue soared by 63 percent, crossing the 20 billion dollar threshold for the quarter. More telling is the monetization metric within that envelope: revenue derived specifically from products built on Google Cloud generative artificial intelligence increased by 800 percent. Furthermore, Google's total cloud backlog nearly doubled to an astonishing 462 billion dollars. This massive backlog represents multi-year contractual commitments from global enterprises, proving that large corporations are locked into long-term cloud architecture strategies built explicitly around artificial intelligence capabilities. Microsoft reported a parallel trend, with total cloud revenue jumping 29 percent to 54.5 billion dollars, led by a 40 percent expansion in Azure revenue that was heavily weighted toward artificial intelligence consumption.
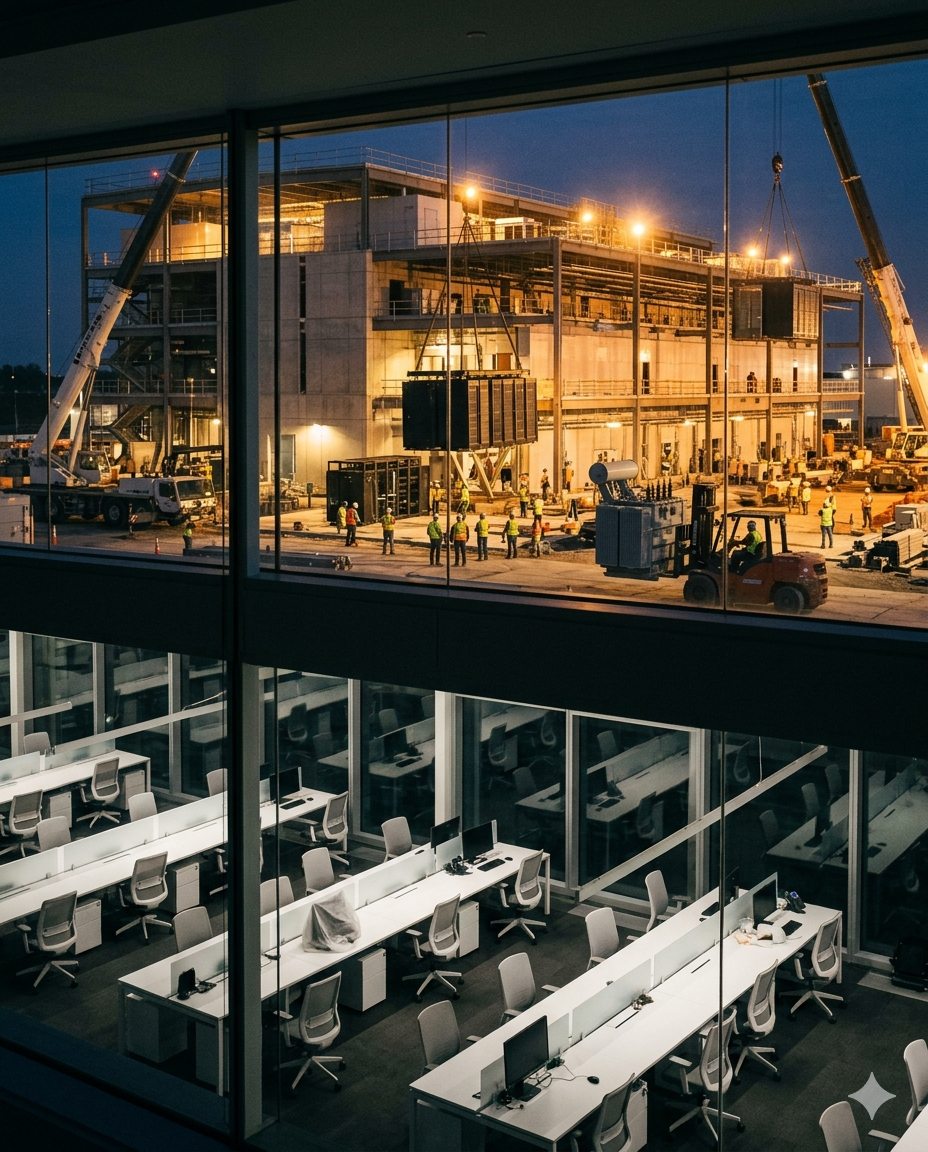
The Structural Shift from Seat-Based Software to Agentic Computations
The economic forces driving this historic infrastructure build-out are fundamentally disrupting the traditional software-as-a-service monetization model that has governed Silicon Valley for more than two decades. Since the inception of modern cloud computing, software enterprises have generated revenue through seat-based licensing models, charging corporations a fixed monthly or annual fee per human user. This monetization mechanism incentivized software companies to design interfaces that maximized human engagement and mandated manual administrative workflows.
The commercialization of agentic artificial intelligence architectures is rendering the seat-based SaaS model obsolete. As autonomous AI agents transition into live production environments, they are actively replacing discrete, human-operated software applications. These advanced agentic systems do not require traditional user interfaces; they interact directly via application programming interfaces, executing complex, multi-step business logic, data synthesis, and system cross-communication without human intervention.
Structural Shifts in SaaS Monetization Models
| Legacy SaaS Model | Emerging Agentic Infrastructure |
|---|---|
| Per-user monthly seat licensing fees | Token consumption and compute utilization billing |
| Optimization for human interface engagement | Optimization for raw API throughput and logic execution |
| Value derived from individual worker enablement | Value derived from autonomous labor substitution |
| Linear revenue scaling tied to customer headcount | Exponential scaling tied to autonomous workload intensity |
Consequently, legacy software revenue streams are beginning to erode. When a corporation deploys an autonomous agentic network capable of performing the data entry, customer service orchestration, or financial auditing previously handled by an entire department, the requirement for individual software licenses evaporates. A corporate department that once required five hundred individual software seats may now only require a single, centralized orchestrator license. This shift creates intense structural deflation for traditional software providers who fail to adapt their pricing models.
To survive this transition, the technology ecosystem is migrating toward consumption-based and outcome-based monetization strategies. Instead of charging for human access, vendors are increasingly billing clients based on compute utilization, tokens processed, or specific business objectives successfully executed by autonomous agents. This transformation shifts the source of software value from human productivity enhancement to autonomous labor substitution.
This architectural shift is also rearranging market leadership among frontier model developers. The enterprise market is demonstrating a highly pragmatic preference for models that optimize cost, speed, and contextual accuracy over pure conversational novelty. Recent market data reveals that Anthropic has successfully unseated OpenAI as the leading large language model provider for business applications within key enterprise sectors. Enterprise buyers are shifting their spending toward Claude because its structural architecture aligns more efficiently with complex, multi-layered document analysis and enterprise-grade data security requirements. This shifting allegiance underscores the volatility of the software layer: enterprise loyalty is tied strictly to infrastructural integration and operational efficiency, rather than brand recognition or consumer-facing features.
The Personnel Paradox: Funding Infrastructure via Human Attrition
The most controversial and defining characteristic of this technology super-cycle is the stark disconnect between record corporate revenues and contracting workforce headcounts. The technology sector is navigating a brutal corporate paradox where historic profits are achieved not by scaling human capital, but by aggressively liquidating it. The decision by four major technology corporations to eliminate 58,000 professional positions in a single quarter is not a reactionary measure to economic recession; it is a calculated, proactive strategy to reallocate capital from human payrolls to silicon infrastructure.
Oracle’s structural reorganization offers a clear blueprint of this macroeconomic shift. By cutting approximately 18 percent of its global workforce, the enterprise database giant freed up billions of dollars in recurring operational expenditure. These savings are being funneled directly into the physical foundations of the next economy: a projected 50 billion dollar capital expenditure campaign dedicated to building and equipping massive data centers. This corporate trade-off reveals that an employee seat is now viewed by corporate leadership as a direct capital competitor to a server rack.
Microsoft is executing an identical strategy. Even as its annual artificial intelligence financial run rate reached a historic 37 billion dollars—representing a 123 percent increase—executive leadership explicitly signaled that additional workforce reductions are on the horizon. The rationale is clear: the capital intensity of the artificial intelligence infrastructure race requires an unprecedented concentration of financial resources. Building hyperscale data centers, securing thousands of megawatts of electrical power grid capacity, purchasing cutting-edge hardware, and funding the continuous research and development of frontier models requires capital reserves that cannot be maintained alongside large, legacy administrative and engineering workforces.
This phenomenon marks a permanent departure from the traditional technology growth playbook. Historically, when a technology corporation achieved record-breaking revenue growth, it responded by launching massive recruitment campaigns, expanding its corporate campuses, and competing fiercely for human engineering talent. The prevailing corporate logic dictated that human capital was the primary engine of innovation and subsequent revenue generation.
In the current paradigm, data centers, custom silicon, and proprietary data pipelines have replaced human staff as the primary engines of corporate value. The marginal utility of adding another thousand software engineers or corporate administrators has dropped significantly when compared to the marginal utility of deploying an equivalent amount of capital into thousands of additional clusters. The technology industry is systematically building an operational model that requires fewer human workers to generate exponentially larger sums of top-line revenue. This structural decoupling of corporate productivity from human headcount represents a fundamental transformation in the global labor economy.
Ecosystem Ripple Effects: Pressure on Channel Partners and Distributors
The shockwaves generated by this massive reallocation of capital are reverberating throughout the broader technology supply chain, creating intense operational friction for channel partners, value-added resellers, and IT distributors. Historically, these intermediary entities served as the primary distribution mechanism for enterprise technology, earning healthy margins by reselling software licenses, managing local hardware deployments, and providing routine IT consulting services.
The rapid migration toward localized cloud infrastructure and autonomous agentic workflows is compressing these traditional business models from both sides. On the hardware front, the soaring cost of cutting-edge components—such as advanced memory systems, specialized optical networking switches, and artificial intelligence-optimized servers—has dramatically increased the cost of goods sold. Because hardware manufacturers hold immense pricing power due to constrained supplies, channel partners are experiencing severe margin compression. These distributors have minimal room to apply markups, and relief is not projected to materialize before 2027.
Concurrently, the erosion of seat-based software revenue is dismantling the recurring revenue streams that channel partners relied on for stability. As enterprise clients cancel legacy SaaS subscriptions in favor of centralized AI agent deployments, distributors are losing their baseline maintenance and licensing fees. The traditional playbook of simply reselling packaged software suites is no longer financially viable.
To survive, the IT distribution ecosystem is forced to undergo an immediate, high-stakes operational pivot. Partners must transition away from transactional product brokering and reinvent themselves as deep systems integrators and specialized architectural orchestrators. The current corporate landscape requires partners who can design and deploy complex, hybrid-cloud environments capable of supporting agentic workloads. This requires highly specialized technical expertise in high-performance networking configuration, distributed data architecture layout, and custom localized model deployment. Distributors who can successfully manage the complex integration of custom enterprise data pipelines with frontier AI infrastructure are finding highly lucrative consulting opportunities. Conversely, those who remain dependent on traditional software reselling are facing rapid obsolescence.
Hardware Diversification and the Silicon Supply Chain Crisis
As the total capitalization of the tech titans positions the industry to surpass an aggregate revenue mark of 3 trillion dollars this year, the absolute dependence on global hardware manufacturing infrastructure has become the industry's single largest vulnerability. The race to deploy enterprise-scale artificial intelligence has triggered a secondary crisis in the hardware supply chain, characterized by extreme resource competition, geopolitical maneuvering, and a desperate scramble to diversify away from monolithic single-source providers.
While Nvidia's massive 62 billion dollar data center quarter confirms its near-monopoly on the high-end processing market, the vulnerabilities of this dependency have forced major tech companies to invest heavily in proprietary silicon designs. Google’s persistent development of its Tensor Processing Unit infrastructure has allowed the company to shield itself partially from the pricing pressures and supply constraints plaguing the rest of the industry. This internal capability is a primary reason Google Cloud was able to accommodate an 800 percent increase in generative AI product workloads without facing debilitating operational bottlenecks.
The diversification effort extends beyond the processing units themselves. The technical demands of running modern agentic workloads have exposed severe performance bottlenecks in legacy networking and memory architectures. An autonomous agent network executing thousands of concurrent, multi-modal database queries requires massive data transmission speeds with minimal latency. Consequently, the enterprise market is funneled into a hyper-focused investment cycle centered on ultra-high-speed optical networking equipment, high-bandwidth memory modules, and specialized liquid-cooling infrastructure designed to prevent high-density server racks from overheating.
This extreme concentration of physical assets has placed unprecedented pressure on global industrial supply chains. The production of advanced memory chips and specialized networking microcomponents relies on a highly fragile, geographically concentrated network of semiconductor foundries and advanced packaging facilities. Any disruption in this network—whether driven by logistical bottlenecks, resource scarcity, or shifting trade restrictions—poses an immediate threat to the multi-billion dollar capital expenditure plans of the tech titans. The real competitive moat in modern technology is no longer just the mathematical sophistication of an algorithm; it is the physical ownership and guaranteed access to the hardware supply chain required to execute that algorithm at scale.
The Geopolitical and Regulatory Superstructure
The rapid evolution of artificial intelligence from a commercial novelty into critical state-level infrastructure has fundamentally altered the relationship between technology corporations and sovereign governments. The immense concentrations of capital and computational power managed by the tech titans are now treated as matters of national security, economic sovereignty, and geopolitical dominance.
This political reality is directly shaping international trade policies and corporate strategies. The ongoing negotiations and potential policy shifts regarding semiconductor export restrictions and international technology transfers have introduced an element of permanent volatility into the corporate planning cycles of major tech companies. Executives from enterprises like Apple and Tesla are forced to engage directly in high-level diplomatic dialogues to safeguard their global manufacturing pipelines and market access. The threat of sudden regulatory interventions or localized chip embargoes requires technology firms to maintain highly adaptable logistical frameworks and invest heavily in domestic manufacturing initiatives.
Within the United States, this state-level prioritization is reflected in significant federal interventions aimed at securing technological leadership. The Department of Commerce's recent issuance of letters of intent to distribute federal incentives under the CHIPS and Science Act underscores the strategic imperative of emerging computing modalities. By funding a diverse portfolio of manufacturing infrastructure and targeted development capital for specialized computing systems, the state is actively trying to build a resilient, domestic hardware ecosystem. This federal capital injection focuses heavily on unresolved engineering bottlenecks such as device reproducibility, error rates, and advanced packaging materials. This proves that the government recognizes that future economic and military superiority depends entirely on domestic mastery of the physical computing fabric.
Simultaneously, state-level and regional governments are stepping into the regulatory vacuum created by the absence of comprehensive global consensus on artificial intelligence governance. Instead of waiting for centralized federal frameworks, individual states are enacting targeted, sector-specific rules designed to govern high-stakes deployments of automated systems, particularly within sensitive domains like healthcare, financial services, and employment auditing. These emerging legal frameworks require model developers and enterprise users to maintain strict data provenance visibility, eliminate vague marketing claims regarding autonomy, and establish hard human-in-the-loop sign-off protocols for high-risk automated decisions. Consequently, compliance has transformed from a routine legal box-checking exercise into a core commercial requirement that dictates product design and market entry strategies for technology founders.
Enterprise Consumption Realities and the Labor Disruption
While the macroeconomic data paints a picture of historic financial growth and systemic architectural change, the true impact of this technology cycle is best understood by examining the operational transformations occurring inside global enterprises. The fact that everyday artificial intelligence usage has become standard across non-technical corporate departments demonstrates that automated workflows are fundamentally rewriting job descriptions and corporate operational workflows.
In fields ranging from corporate law and financial compliance to human resources and marketing, non-technical personnel are utilizing advanced language models and automated workflows to perform tasks that previously consumed hours of manual labor. The primary use cases have evolved beyond simple text generation into complex data classification, multi-language synthesis, automated code review, and localized strategic modeling.
A corporate department that once required hundreds of human software seats is transforming into an architectural environment where capital is directed to raw compute power rather than headcount.
This deep integration of automation into everyday corporate operations is triggering a structural redesign of internal labor architectures. When a mid-level manager can leverage an automated platform to draft comprehensive compliance reports, manage international scheduling, track departmental expenditures, and perform preliminary market research, the structural necessity for large junior teams and administrative support personnel diminishes. This operational reality is the direct driver behind the broader enterprise headcount stagnation and targeted reductions occurring outside the core technology sector. Corporations are learning to achieve significantly higher output per employee by replacing entry-level administrative labor with continuous, machine-learning-driven workflows.
This operational shift has exposed a critical capability gap within the enterprise landscape. Many corporate organizations are discovering that while the deployment of autonomous systems increases short-term efficiency, it introduces unprecedented operational risks if not coupled with rigorous domain expertise. The reliance on automated outputs without mature human oversight can lead to systemic data leaks, regulatory non-compliance, and costly strategic errors. As a result, the premium on human labor has shifted dramatically: corporate value is no longer tied to a worker's ability to execute repetitive, high-volume tasks, but rather to their capacity for high-level critical judgment, algorithmic auditing, and specialized domain oversight.
The Looming Infrastructure Bottleneck: Energy and Land
As the tech titans aggressively reallocate their record profits into expanding their physical computing footprints, they are confronting an unyielding physical barrier that cannot be optimized away by software engineering: the finite availability of electrical energy and industrial land. The computational intensity required to sustain continuous, large-scale inference and agentic processing workloads has transformed data centers into some of the most energy-dense structures on the planet.
The scaling plans of hyperscalers are creating immense strain on regional electrical grids. Modern data center clusters require hundreds of megawatts of continuous, uninterrupted power to keep processing units functioning and cooling systems operational. This surging demand has outpaced the generation and transmission capacities of many regional utility providers, leading to a fierce competitive scramble among tech giants to secure long-term energy contracts. This energy bottleneck is forcing tech companies to engage in unprecedented capital investments outside the traditional boundaries of the technology sector, including financing dedicated nuclear energy restarts, investing heavily in utility-scale renewable energy projects, and exploring experimental on-site power generation technologies.
Land availability has emerged as a parallel constraint. Building a modern, hyperscale data center requires vast tracts of industrial land equipped with robust access to high-voltage power lines and transcontinental fiber-optic networking trunks. The geographic areas that meet these criteria are rapidly experiencing severe land scarcity, driving real estate values to historic highs and triggering intense zoning and political battles within local communities. Residents and local governments are increasingly pushing back against data center developments due to concerns over local resource consumption, noise pollution from cooling infrastructures, and the minimal long-term human employment these massive facilities bring to a region. The ability to navigate these complex socio-political and environmental bottlenecks has become a critical operational requirement for technology executives, proving that the ultimate limitation on the growth of the digital economy is firmly rooted in the physical realities of the material world.
Capital Allocation Strategies for the Next Computing Epoch
The financial records and stark operational restructurings defining the current tech landscape confirm that the global technology sector has entered a period of permanent structural transition. The unprecedented aggregation of wealth among a handful of dominant technology conglomerates—on track to easily clear the 3 trillion dollar mark—has created a corporate elite with the financial capacity to reshape global industrial reality.
The core narrative of this epoch is no longer about technological innovation in a vacuum; it is about the hyper-aggressive, calculated consolidation of computational infrastructure, physical resources, and market access. The tech titans have clearly determined that the future of economic value generation belongs entirely to automated, agentic systems running on proprietary silicon hosted within sovereign, energy-secure data center networks. Every corporate decision made today—from the systemic elimination of tens of thousands of human workers to the multi-billion dollar capital expenditure commitments—is aligned with this singular architectural vision.
For founders, enterprise executives, and market strategists navigating this landscape, the implications are absolute. The traditional models of building software applications, monetization strategies, and managing corporate workforces have been fundamentally disrupted. Success in this new era requires a total rejection of legacy playbooks and a clear-eyed acceptance of the new economic realities. The technology market has matured beyond the playground of shiny demonstrations and speculative valuation metrics; it is now an industrialized arena governed by raw computational scale, structural infrastructure control, and rigid regulatory frameworks. The enterprises that successfully align their operations with this structural shift are capturing unprecedented shares of global wealth, while those that remain tethered to the human-centric configurations of the past are facing systematic disruption and rapid economic obsolescence.
1
0
0
0

মন্তব্য